Esta
An agent-led lending and wallet platform for Nigeria: “Fast loans. Clear repayments.” It has moved about ₦1.5 billion so far. We built three web portals, then the mobile app.
- Combined volume moved (≈ $1.1M)
- ₦1.5B
- Outflows: loans and withdrawals
- ₦1.0B
- Inflows: savings and repayments
- ₦500M
The problem
Clients join Esta through an agent, take loans within limits set by that agent’s class, save in naira wallets and repay by card. That meant three products in one (clients, agents and the ops team) where every naira has to be accounted for and identity checks get stricter as the money gets more serious.
Key decisions
One KYC gate, stronger checks where the risk is
Signing up is quick: phone, agent referral code, OTP and PIN, then one onboarding step for personal details, next of kin and security questions. The heavy checks (BVN, bank-name match, selfie with face-quality checks, documents by agent class) sit on the loan path, where they matter.
Limits follow the agent and the loan
What a client can borrow or withdraw depends on their agent’s class and their loan state, not on KYC tiers. For example, savings withdrawals can be held while a loan is active.
Three portals, one ledger
Clients borrow, save and repay; agents refer, verify in the field and earn commission; admins underwrite, approve payouts and configure the system. Each portal sees the same money from its own side.
Wallets with clear rules
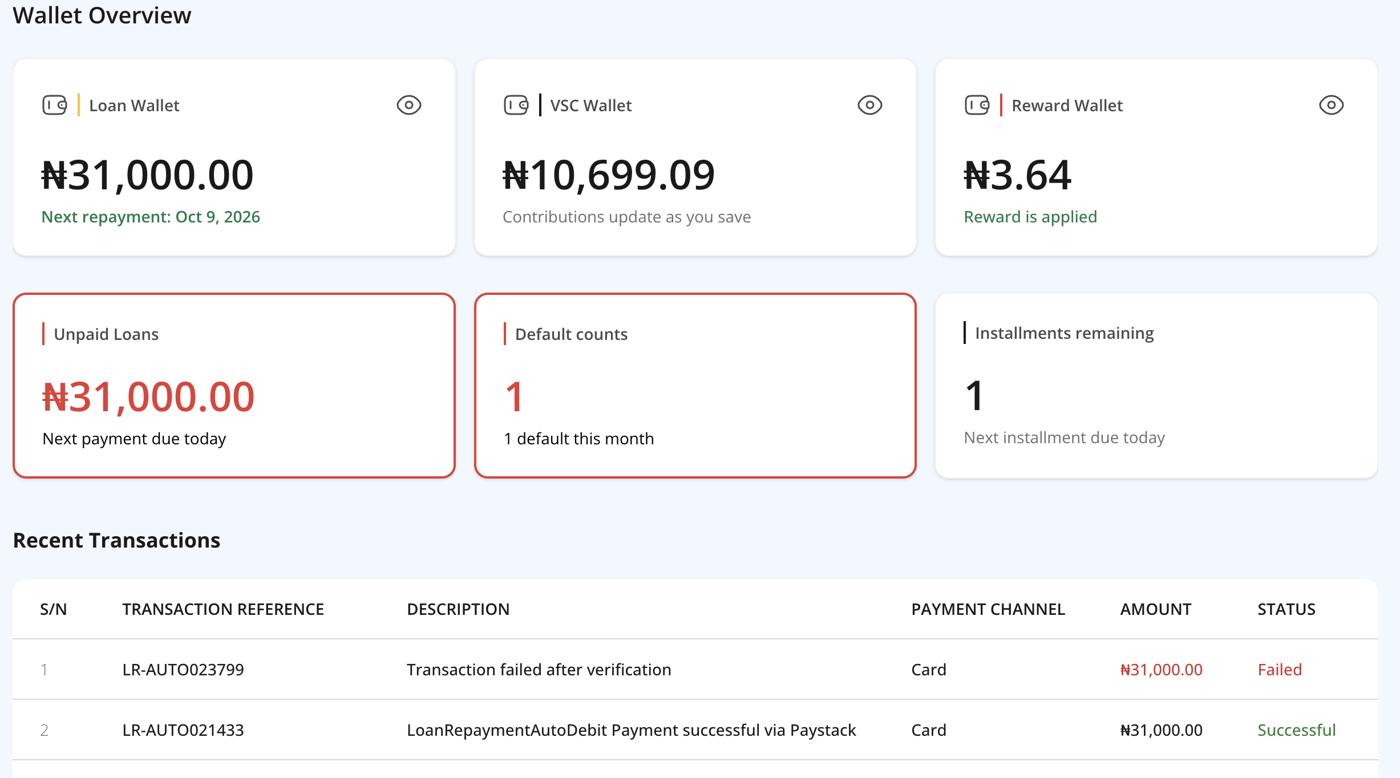
Savings wallets take top-ups and approved bank withdrawals; reward credits can move to savings or be withdrawn; loans disburse only to verified bank accounts and repay through Paystack.
Outcome
- About ₦1.5 billion (≈ $1.1M) in combined flows so far: roughly ₦1.0B out and ₦500M in.
- Client, agent and admin portals live on the web, followed by the mobile app.